Written Commentary

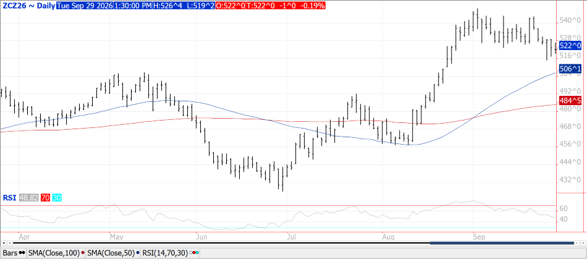
Prices were $.01-$.02 lower in 2-sided trade while spreads were mixed. Dec-26 futures held within Monday’s range. O.I. was down 5.4k contracts. Crop conditions held steady at 57% G/E. Overall ratings held at the crop cycle lows and just below the historical average. 96% of the crop is dented while 72% is mature, both slightly above YA and the 5-year Ave. Harvest has reached 18%, matching the 5-year Ave. while just above the YA pace of 17%. Updated ratings suggest an average US yield of 178.3 bpa with production at 15.784 bil. bu. up 10 mil. from last week while just below the USDA forecast at 15.80 bil. bu. The Reuters survey shows analysts expect Sept. 1st US corn stocks at 1.918 bil. bu. vs. 1.551 bil. YA and down slightly the USDA Sept-26 WASDE estimate of 1.922 bil. EU imports for 26/27 MY as of Sept. 27th at 4.96 mmt are up 34% YOY. While the removal of tariffs to China makes US corn more competitive, US Gulf FOB offers remain $.10-$.20 bu. over Brazilian offers while $.30-$.60 over Argentina through the end of 2026. US FOB corn will likely have to fall back below Brazil before China shows interest in US.
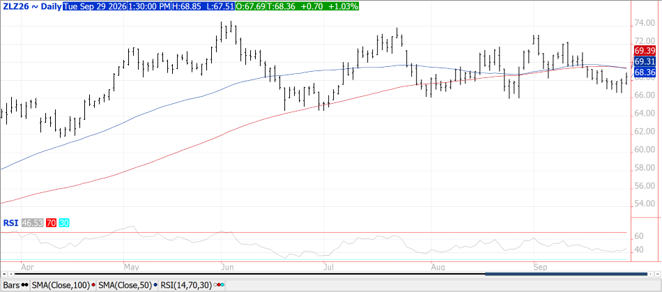
Mostly higher trade across the complex with beans up $.08-$.10, meal was steady to $1.50 lower while oil jumped 70-75 points. Nov-26 beans held within yesterday’s range while briefly trading back above $13 bu. Dec-26 meal fell to a 2-week low before bouncing. Dec-26 oil has MA resistance at 69.30. Speculative traders were back in a buying mood today after sources suggested China was seeking offers for US beans at the Gulf and off the PNW. Soybean O.I. was down 19.4k contracts, meal was off just over 16k while oil was down 22.5k. Rain continues to impact the WCB and plain states while the C. Midwest and ECB experience favorable harvest conditions. That pattern looks to hold for a few more days before remnants of Hurricane Polo brings another round of heavy rain across the nation’s midsection. Harvest progress will remain slow in the WCB until dryer conditions settle in late this week. Week 2 of the outlook brings below normal precipitation across much of the Midwest. Crush margins slipped $.02 ½ to $2.44 bu. with meal PV slipping to 51.2%. Crop conditions held steady at 58% G/E. Composite ratings remain at crop cycle lows while just above the historical average. Ratings improved in 6 states, declined in 8 while holding steady in 4. 75% of the crop is dropping leaves matching the 5-year Ave. while just below 76% YA. Harvest has reached 17%, also matching the 5-year Ave. while just below the 18% pace from YA. Updated ratings suggest an average US yield of 52.5 bpa with production at 4.508 bil. bu. down 3 mil. bu. from last week while below the USDA forecast of 4.535 bil. The Reuters survey shows traders expect Sept. 1st US bean stocks at 324 mil. bu. vs. 325 mil. YA which was also the USDA Sept-26 WASDE estimate for 25/26 ending stocks. AgRural places Brazil’s soybean plantings at 3.4% just above the YA pace of 3.2%. US Gulf FOB offers remain $.10-$.20 below Brazil into year end.
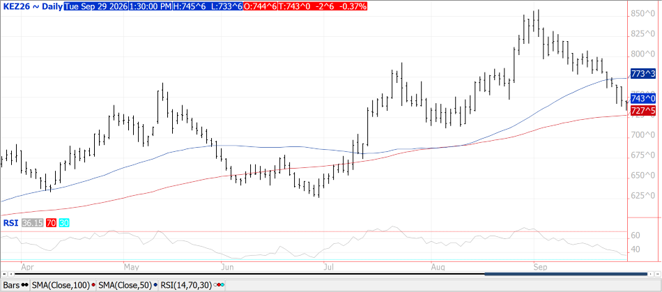
Prices ranged from $.03 lower to $.04 higher. CGO Dec-26 was up $.04 at $6.92 ¾. Dec-26 KC was off $.02 ¾ at $7.43 having fallen to a 7-week low. Dec-26 MIAX was down $.02 ½ at $6.99 ¼ also reaching a 7-week low. CGO wheat O.I. was down 2k contracts, while KC was off 3.4k. Ukraine’s Ag. Minister stated his country feels there will be no cease fire for Black Sea shipping for several months. IKAR estimates Russia was able to ship 2.3 mmt of wheat in Sept-26, up from recent estimates of 2.1-2.2 mmt. The Reuters survey shows traders expect all US wheat production at 1.524 bil. bu., down from 1.531 bil. in Aug-26. Sept. 1st stocks are expected at 1.872 bil., well below the 2.134 bil. YA. WW plantings advanced 10% to 27%, below the 32% pace from YA and the 5-year Ave. of 34%. 8% of the crop has emerged vs. the 5-year Ave. of 11%. Rains in the plains will continue to help ease drought conditions. EU soft wheat exports as of Sept. 27th at 6.8 mmt is steady with YA. So far the collapse of Black Sea grain shipments has not led to an increase in US exports.
Risk Warning: Investments in Equities, Contracts for Difference (CFDs) in any instrument, Futures, Options, Derivatives and Foreign Exchange can fluctuate in value. Investors should therefore be aware that they may not realise the initial amount invested and may incur additional liabilities. These investments may be subject to above average financial risk of loss. Investors should consider their financial circumstances, investment experience and if it is appropriate to invest. If necessary, seek independent financial advice.
ADM Investor Services International Limited, registered in England No. 02547805, is authorised and regulated by the Financial Conduct Authority [FRN 148474] and is a member of the London Stock Exchange. Registered office: 3rd Floor, The Minster Building, 21 Mincing Lane, London EC3R 7AG.
A subsidiary of Archer Daniels Midland Company.
© 2026 ADM Investor Services International Limited.
Futures and options trading involve significant risk of loss and may not be suitable for everyone. Therefore, carefully consider whether such trading is suitable for you in light of your financial condition. The information and comments contained herein is provided by ADMIS and in no way should be construed to be information provided by ADM. The author of this report did not have a financial interest in any of the contracts discussed in this report at the time the report was prepared. The information provided is designed to assist in your analysis and evaluation of the futures and options markets. However, any decisions you may make to buy, sell or hold a futures or options position on such research are entirely your own and not in any way deemed to be endorsed by or attributed to ADMIS. Copyright ADM Investor Services, Inc.