Written Commentary

Prices
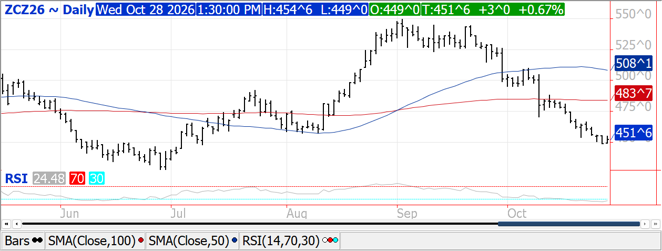
were steady to $.03 higher while spreads firmed. Dec-26 futures ended a run of 4 consecutive lower closes. Speculative traders sold another 12k contracts yesterday, reducing their long position to 126k. They were likely modest buyers today. O.I. from yesterday however was up 19k contracts, an indication of fresh shorts entering the market, likely offset by end user buying taking advantage of the price collapse. That said however, the path of least resistance remains lower until US demand improves and/or we see a more threatening SA forecast. Ethanol production increased to 329 mil. gallons last week, up from 322 mil. the previous week while up 2.5% YOY. Production was above expectations. There was 110 mil. bu. of corn used in the production process, or 15.7 mil. bu. per day, above the 15.56 mbd needed to reach the USDA usage forecast of 5.650 bil. bu. Stocks slipped to 24.5 mil. barrels, still well above the 22.4 mb from YA. Production margins remain firm as energy prices remain high while corn and natural gas prices slide. Tomorrow’s export sales are expected to range from 40-65 mil. bu.
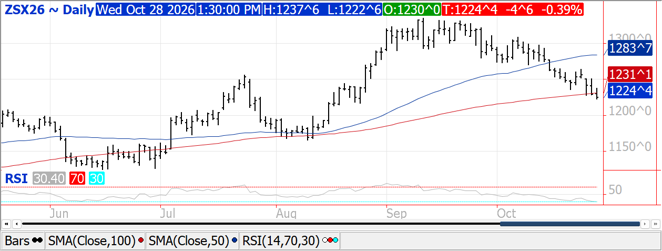
Prices closed mostly lower today with beans down $.05-$.07, meal was mixed and within $1 of unchanged, while oil was off over $.01 lbs. Nov-26 futures closed into new 2-month lows and below its 100-day MA support. Bean and meal spreads firmed while oil spreads weakened. Dec-26 meal violated support at its 100-day MA before bouncing. Dec-26 oil closed into a 4-month low. Crush margins slipped $.05 to $2.35 bu., reaching a 2-month low, while bean oil PV fell to 49.4%. Light rain will favor the WCB and Great Lakes region the next few days before widespread showers fill in across the central and southern Midwest this weekend into early next week. Above normal temperatures look to hold across the nation’s midsection through the first week of Nov-26, while a dryer outlook in the NW corn belt will improve harvest conditions. The USDA announced a flash sale of 120k mt of soybeans to an unknown buyer. Chinese purchases likely rest between 18-19 mmt. Sinograin is expected to auction off another 400k mt of soybeans next Tues. Nov. 3rd. Their last auction earlier this week sold only 172k mt, roughly a third of the total volume offered. After yesterday’s trade we have the MM long position across the soybean complex at 460k contracts, still historically large, however off from the recent record of 558k. Soybean O.I. was down 6.5k contracts, meal was off 1.4k while oil was down 4.3k. Soybean plantings in Parana at 62%, Brazil’s 2nd largest producing state, trail the YA pace of 71%. While the recent plunge in the Brazilian Real will not do much to benefit Brazil’s exports with global trade priced in dollars, it has helped improve the bottom line for Brazilian farmers. Not likely to impact their 2026/27 acreage mix. Tomorrow’s export sales are expected to range from 50-100 mil. bu. of soybeans, 200-450k tons of meal and 0-10k tons of oil.
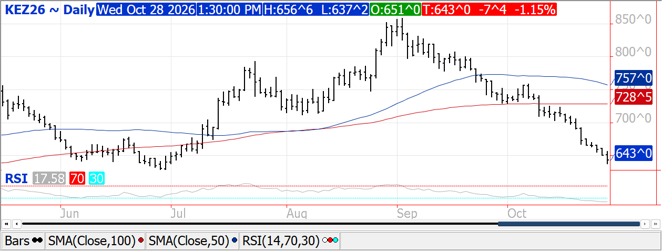
Prices ranged from $.07 to $.11 lower with all 3 classes falling to fresh 4-month lows. CGO Dec-26 was $.11 lower at $5.99, Dec-26 KC is down $.07 ½ at $6.43 while Dec-26 MIAX was $.09 lower at $6.19 ¾, while establishing a new contract low. Wheat was the early downside leader as hopes for the safe passage of agricultural goods from the Black Sea region have improved. Russia issued a permit for a vessel carrying grain to leave the Sea of Azov via the Kerch Strait for the first time since July. Wire services report the Kerch Strait will reopen through Nov. 15th using Naval escorts to help secure safe passage. Only time will tell whether a recent cease-fire agreement in the city of Oleshky in the Kherson region will hold (or expand) or whether vessels will be able to safely navigate through the Black Sea. Hopes for peace have pressured prices the past 2 months. I’d estimate the MM short position in CGO is approaching 70k contracts after today’s trade. Friday’s CFTC data will likely show MM’s have flipped to short in both KC and MIAX for the 1st time in 3-4 months. Still trying to firm up a date for trilateral peace talks between US, Russia and Ukraine, meanwhile the fighting continues. Tunisia reportedly bought 100k mt of soft wheat in today’s tender is just under $297/mt CF. Tomorrow’s export sales are expected to range from 8-18 mil. bu.
Risk Warning: Investments in Equities, Contracts for Difference (CFDs) in any instrument, Futures, Options, Derivatives and Foreign Exchange can fluctuate in value. Investors should therefore be aware that they may not realise the initial amount invested and may incur additional liabilities. These investments may be subject to above average financial risk of loss. Investors should consider their financial circumstances, investment experience and if it is appropriate to invest. If necessary, seek independent financial advice.
ADM Investor Services International Limited, registered in England No. 02547805, is authorised and regulated by the Financial Conduct Authority [FRN 148474] and is a member of the London Stock Exchange. Registered office: 3rd Floor, The Minster Building, 21 Mincing Lane, London EC3R 7AG.
A subsidiary of Archer Daniels Midland Company.
© 2026 ADM Investor Services International Limited.
Futures and options trading involve significant risk of loss and may not be suitable for everyone. Therefore, carefully consider whether such trading is suitable for you in light of your financial condition. The information and comments contained herein is provided by ADMIS and in no way should be construed to be information provided by ADM. The author of this report did not have a financial interest in any of the contracts discussed in this report at the time the report was prepared. The information provided is designed to assist in your analysis and evaluation of the futures and options markets. However, any decisions you may make to buy, sell or hold a futures or options position on such research are entirely your own and not in any way deemed to be endorsed by or attributed to ADMIS. Copyright ADM Investor Services, Inc.