Written Commentary

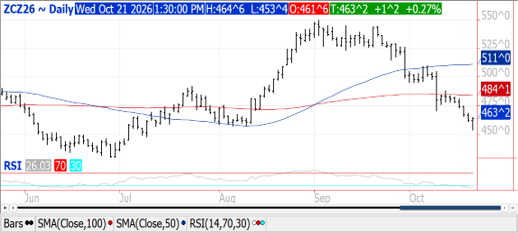
Prices were $.01-$.02 higher in volatile 2-sided trade. Spreads were little changed. Dec-26 plunged to a 3 ½ month low before recovering while avoiding a 7th consecutive lower close. Today’s low at $4.53 ½was right at its 50-week MA support. We had the MM long position down to 182k contracts entering today’s trade. Open interest was up just over 6k contracts. Friday’s COF report is expected to show cattle inventories at 11.441 mil. head as of Oct. 1st, slightly above 11.418 mil. YA. Placements are expected to be down 8.3% while marketing off 7.3%. Brazil’s exports in Oct-26 are expected to reach 6.87 mmt, vs. 5.69 mmt YA. Ethanol production increased to 322 mil. gallons last week, up from 313 mil. the previous week while up 2% YOY. Production was in line with expectations. There was 107 mil. bu. of corn used in the production process, or 15.34 mil. bu. per day. In the MY to date there has been 685 mil. bu. used, or 14.9 mbd, an annualized pace of 5.432 bil. bu., below the USDA forecast of 5.650 bil. bu. Stocks rose to 24.6 mil. barrels, above 22.6 mb from YA. Production margins are firm as energy prices remain high while corn prices have slid. SovEcon lowered Ukraine’s grain export forecast another 5.1 mmt to only 33 mmt. Corn exports were cut 3.8 mmt. For prices to form a meaningful bounce, we’ll need to see improved demand and/or a more threatening forecast in SA. Tomorrow’s export sales are expected to range from 28-60 mil. bu.
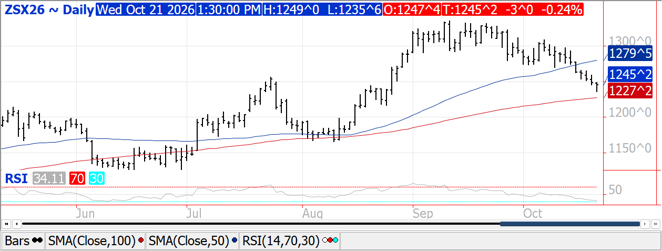
Prices were lower across the complex however all contracts managed to bounce off session lows. Beans were $.03-$.09 lower, meal was down $1-$3 while oil was off 70-80 points. Bean and meal spreads firmed while oil spreads were mixed. Nov-26 beans fell to a fresh 2-month low while closing lower for an 8th consecutive session. Fibonacci support is at $12.29 while 100-day MA support is at $12.27 ¼. Dec-26 oil fell to a 3 ½ month low before recovering. Light rains in the C. Plains yesterday, otherwise dry conditions across the Midwest. Showers to impact the Plains and portions of the WCB this weekend into early next week while dry conditions across the rest of the nation’s midsection should allow US harvest to get back on track. Crush margins are off another $.06 at $2.47 bu. with meal PV improving to 51.4%. Soybean O.I. was up 12.8k contracts, down 9.4k in meal while oil was up just over 1k contracts. The USDA announced flash sales of 134k mt of soybeans to China and 165k mt to Spain. Chinese purchases likely sitting near 17.5 mmt. China’s Sinograin will auction off another 512k mt of soybeans from Govt. reserved next Tues. the 27th. I believe the USDA export forecast at 1.695 bil. bu. (46.1 mmt) will prove to be too low. US Gulf FOB offers holding $.20-$.30 below Brazilian offers into the end of the year. Brazil’s exports are expected to reach 6.4 mmt in Oct-26 vs. 6.54 mmt YA. US harvest likely reaching 80%+ by the end of this weekend. Tomorrow’s export sales are expected to range from 65-110 mil. bu. of beans, 250-650k tons of meal with oil between 0-10k tons.
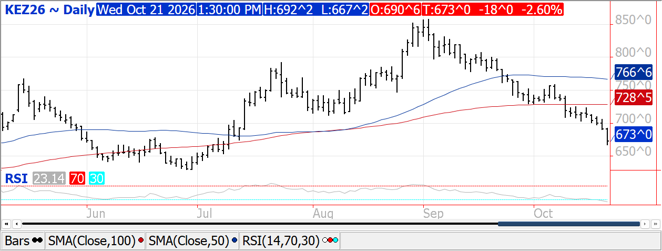
Prices were $.09 to $.18 lower today with all 3 classes trading to fresh 3-month lows. CGO Dec-26 was $.15 lower at $6.28 ¼, Dec-26 KC was off $.18 at $6.73 while Dec-26 MIAX was down $.10 ¼ at $6.51 ½. Wheat was the downside leader as war premium was extracted from global prices after Ukraine Pres. Zelensky stated he would accept a peace deal that freezes front lines as a “real way to end this war.” After yesterday’s close we had the MM short position in CGO wheat back up to 43k contracts, the largest in 3 months, perhaps pushing 50k with today’s selling. NATO has discussed security in the Black Sea recently while deciding to send “additional assets to the region.” Iran has been the largest importer of Russian grain since the start of the 2026/27 MY in July. Their grain imports have reached 1.72 mmt, Egypt comes in 2nd at 1.35 mmt while Azerbaijan a distant 3rd with .545 mmt. SovEcon lower Ukraine’s export forecast another 1.2 mmt. The recent pullback should enable US wheat to be more competitive in the global marketplace. Export sales are expected to range from 10-20 mil. bu.
Risk Warning: Investments in Equities, Contracts for Difference (CFDs) in any instrument, Futures, Options, Derivatives and Foreign Exchange can fluctuate in value. Investors should therefore be aware that they may not realise the initial amount invested and may incur additional liabilities. These investments may be subject to above average financial risk of loss. Investors should consider their financial circumstances, investment experience and if it is appropriate to invest. If necessary, seek independent financial advice.
ADM Investor Services International Limited, registered in England No. 02547805, is authorised and regulated by the Financial Conduct Authority [FRN 148474] and is a member of the London Stock Exchange. Registered office: 3rd Floor, The Minster Building, 21 Mincing Lane, London EC3R 7AG.
A subsidiary of Archer Daniels Midland Company.
© 2026 ADM Investor Services International Limited.
Futures and options trading involve significant risk of loss and may not be suitable for everyone. Therefore, carefully consider whether such trading is suitable for you in light of your financial condition. The information and comments contained herein is provided by ADMIS and in no way should be construed to be information provided by ADM. The author of this report did not have a financial interest in any of the contracts discussed in this report at the time the report was prepared. The information provided is designed to assist in your analysis and evaluation of the futures and options markets. However, any decisions you may make to buy, sell or hold a futures or options position on such research are entirely your own and not in any way deemed to be endorsed by or attributed to ADMIS. Copyright ADM Investor Services, Inc.