Written Commentary

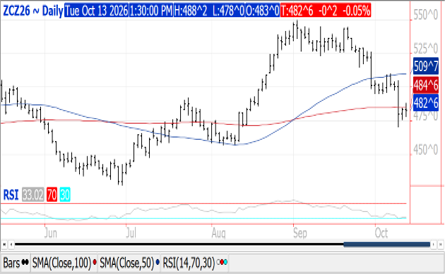
Prices were steady to $.01 lower while spreads were mixed and little changed. Dec-26 rejected trade back above its 100-day MA. Longer term support is at the August low at $4.57 ¼. Open interest plunged nearly 25k contracts yesterday after speculative traders bought 8k contracts extending their long holdings up to 246k contracts. The function of the market now is to find a price level that stimulates demand. China’s COFCO lowered their corn import forecast to only 3.5 mmt for the 2026/27 MY, below the USDA forecast of 5 mmt. They went on to state US supplies were “not an option yet” because they remain uneconomical. Chinese Dalian corn futures premium to US Gulf firmed to $107 per ton, however still well below the $150 level which is more typical when buying US corn. COFCO raised their sorghum import forecast 550k tons to 8 mmt. Farmer sales have slowed since Friday’s sell-off. Since 1990 the USDA lowered corn yields in Aug. and Sept. only to raise them in Oct. 4 times, with this year being the 5th. Three times the final yield was above the October forecast, while 1 year the final yield was steady. AgRural reports Brazil’s 1st crop plantings have advanced to 44%, just below the YA pace of 45%. Export inspections at 51 mil. bu. were in line with expectations. YTD inspections at 33 mil. are up 5% from YA, vs. the USDA forecast of down 4%. Noted buyers were Mexico – 18 mil. while Japan and Korea both took 11 mil.
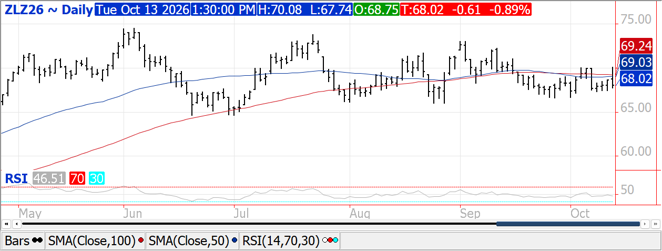
Prices have turned lower across the complex with beans down $.04-$.06, meal was off $2-$4 while oil was down 50-60 points. Bean spreads firmed while product spreads weakened. Support for Nov-26 soybeans is at its 50-day MA at $12.69 ¾. Inside trade for Dec-26 meal while Dec-26 oil rejected trade above $.70 lb., its highest level in a month. Bean oil was lower despite the EPA announcing their intent to reallocate the 1.76 bil. gallons of SRE announced in Aug-26 onto larger refineries. Crush margins fell back $.15 to $2.63 ½ bu. after reaching a 3-month high yesterday. Open interest from yesterday’s trade was down 6.4k in soybeans while up 11.4k in meal and 4.4k in oil. Chinese purchases have slowed since late Sept-26 which we estimate at just over 15 mmt. Officials from COFCO are suggesting Chinese imports in Q4 of 2026 will average near 9.5 mmt per month vs. 8.5 mmt per month in Q4 of 2025. Sinograin sold 210k tons of soybeans in today’s auction, roughly 40% of the volume offered. AgRural reports Brazilian plantings have reached 15% as of Oct. 8th, vs. 14% YA. Since 1990 the USDA lowered yields in August, only to raise them in September and October five times, with this year being the 6th. In the previous 5 years the final yield was above the October forecast 3 times, while below it twice. Export inspections at 40 mil. bu. were below expectations. YTD inspections at 189 mil. are up 27% from YA vs. the USDA forecast of up 12%. China took 24 mil. bu. with Mexico taking 4 mil.
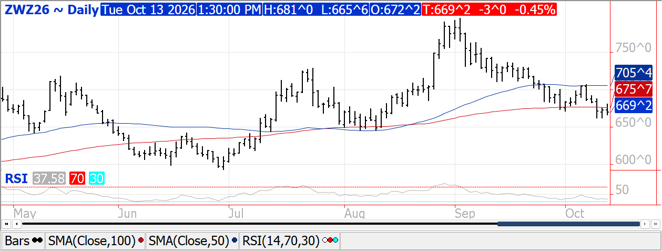
Prices were $.02-$.03 lower in 2-sided trade. CGO Dec-26 was down $.03 at $6.69 ¼, Dec-26 KC was also $.03 lower at $7.12 ¼ while Dec-26 MIAX was $.02 ¼ lower at $6.94. Reports two more ships were struck by Russian drones off the coast of Bulgaria (NATO member) likely fueled an recovery in feed grains. Five crew members were rescued from a vessel that sank, however 11 were still missing. All 15 crew members of the other vessel were rescued. Baltic countries continue to urge the EU to block Russian grain from moving through the region to access ports along the Baltic Sea. IKAR cut Russia’s 2026 wheat production forecast .5 mmt to 88 mmt, matching the USDA est., while lowering their export forecast 1.5 mmt to 42 mmt, vs. the USDA est. of 40 mmt. Rabobank forecasts Australia’s 2026/27 wheat production at 31 mmt, down 13.3% YOY also in line with the USDA. Algeria reportedly bought around 600k mt of milling wheat near $326/mt CF. The grain was likely sourced from Russia via Baltic ports, along with Romania, Bulgaria and Argentina. Shipment is for Dec-26. Export inspections at 11 mil. bu. was in line with expectations. YTD inspections at 256 mil. bu. is down 35% from YA vs. the USDA forecast of down 17%. Traders expect US winter wheat plantings have reached the halfway point.
Risk Warning: Investments in Equities, Contracts for Difference (CFDs) in any instrument, Futures, Options, Derivatives and Foreign Exchange can fluctuate in value. Investors should therefore be aware that they may not realise the initial amount invested and may incur additional liabilities. These investments may be subject to above average financial risk of loss. Investors should consider their financial circumstances, investment experience and if it is appropriate to invest. If necessary, seek independent financial advice.
ADM Investor Services International Limited, registered in England No. 02547805, is authorised and regulated by the Financial Conduct Authority [FRN 148474] and is a member of the London Stock Exchange. Registered office: 3rd Floor, The Minster Building, 21 Mincing Lane, London EC3R 7AG.
A subsidiary of Archer Daniels Midland Company.
© 2026 ADM Investor Services International Limited.
Futures and options trading involve significant risk of loss and may not be suitable for everyone. Therefore, carefully consider whether such trading is suitable for you in light of your financial condition. The information and comments contained herein is provided by ADMIS and in no way should be construed to be information provided by ADM. The author of this report did not have a financial interest in any of the contracts discussed in this report at the time the report was prepared. The information provided is designed to assist in your analysis and evaluation of the futures and options markets. However, any decisions you may make to buy, sell or hold a futures or options position on such research are entirely your own and not in any way deemed to be endorsed by or attributed to ADMIS. Copyright ADM Investor Services, Inc.