Macroeconomics: The Day Ahead for 4 September 2026

Persian Gulf and Black Sea conflicts still casting a long shadow, but  increasing short-term focus on Fed and BoJ policy outlooks; US labour  data tops statistical run, as jump in German Orders, yr/yr slide in  Japan Household Spending are digested; BoE speakers also on tap.
  • U.S.A.: Payrolls seen rebounding modestly, but focus on Unemployment Rate after Warsh played down any labour market concerns; initial market reaction to any Payrolls outliers may prove to be short-lived.
  • Japan: markets and flows point to significant shift in JPY sentiment; JPY heavily undervalued on PPP metrics implies risk of sharper correction.

EVENTS PREVIEW

It’s been a choppy week for markets, and for all the political bluster and the skirmishes between the US and Iran, little has changed; neither side is in any hurry to resume meaningful negotiations, and for all the efforts that are being made to get oil, gas and refined products as well as container traffic through the Strait of Hormuz, traffic remains limited. While the August US labour data tops the agenda, Fed’s Waller made it very clear yesterday that next Friday’s CPI data will be the key factor for the September rate decision. His position does appear to have shifted yet again to a more neutral stance than earlier in the summer, placing rather more weight on not wanting to see any renewed upward pressure, and in contrast to Warsh suggesting policy is marginally restrictive, and minded to hold rates at the September meeting barring an upside CPI surprise. There are also German Factory Orders to digest, with the UK Construction PMI and DMP survey, and Canada’s Unemployment data also ahead. The speech by BoE’s Bailey and parliamentary testimony of Bailey and other MPC members will be of more significance than that of ECB’s Lane, given the ECB has entered its communications blackout period ahead of next week’s policy meeting, while the 2-day Ambrosetti Forum gets under way in Italy, gathering together a number of key European and Italian politicians. Meanwhile, Sunday will see the Sachsen-Anhalt state election, with polls suggesting an outright majority for the far-right AfD, though the greater immediate concern are the run of attempted sabotage attacks this week on the power grid, which some commentators suggest is a consequence of Germany attributing responsibility for a failed, explosive-laden drone attack at Leipzig/Halle Airport to Russian state-sponsored hybrid warfare. On a separate note regarding energy markets, yesterday saw an unusual divergence between Brent Crude and ICE Gasoil, with the latter seeing a sharp drop of >1.0%, despite a rise in Brent, and the divergence continues today with Brent down 0.2% and GasOil down a further 2.0%, and notably no signs that the much discussed pressures on refined product (diesel, jet fuel, etc) supply chains is shifting significantly. Speculative positioning in energy futures has seen a sharp rise in net longs in refined products, so this may be mostly position unwinding, and possibly related to yesterday’s GasOil options expiry.
 

** Japan **

While the overnight Household Spending data was much weaker than expected, the series is volatile, with many expecting a sharp rebound in August, and unlikely to deter the BoJ from a further rate hike. Rather more notable this week has been a clear shift in the fortunes of the JPY and long-term JGB yields, as well as a market re-pricing of the BoJ’s rate trajectory. Markets are always primarily a function of flows and momentum, and as much as Japanese and US political policymakers may want to claim that their rhetoric and recent FX intervention was the driver, it is more likely that Ueda’s hawkish shift, Takata putting an outsized rate hike on the table (he is an outlier, and this is highly unlikely to happen, but the signal is aggressive) that is driving the change in flows. Notably, Japan investors are increasingly net sellers of foreign assets according to weekly flow data, and there appears to be a considerable unwind of JPY-funded carry trades, at least if the reversal in CHF/JPY cross rate is anything to go by (see attached chart).
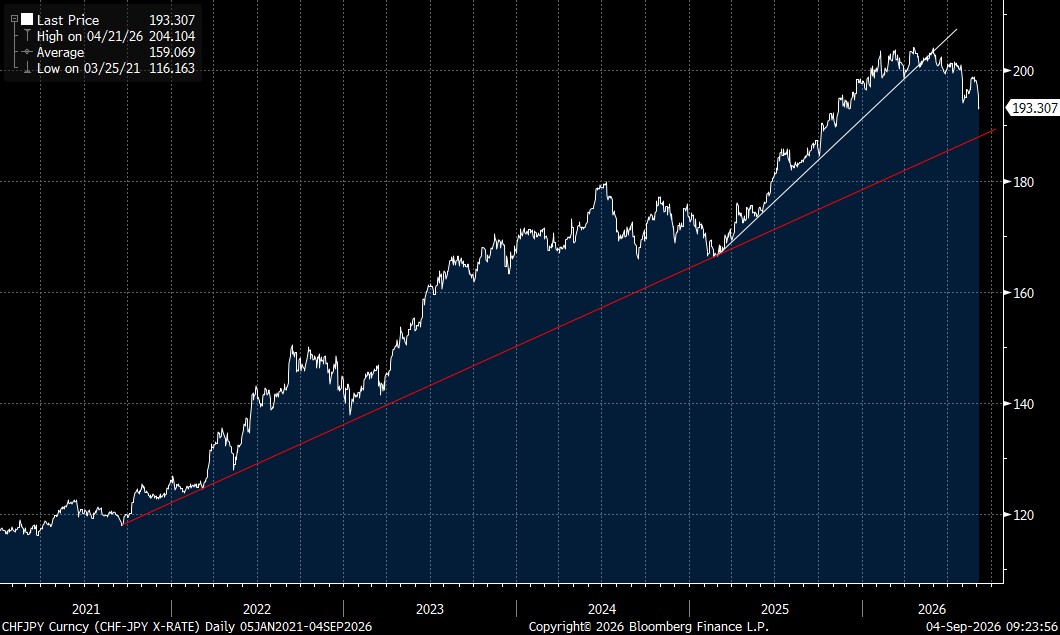
Chart - CHF JPY spot

While unsurprising from the aspect of the BoJ finally tacitly conceding that it is behind the curve, the risk is that with the JPY clearly very undervalued on any Purchasing Power Parity (PPP) metric, the move lower in USD/JPY may prove to be much sharper than many are anticipating. As Finance Minister Katayama has previously opined before she took office, fair value for the JPY may be rather closer to a 120-130 range. While that may seem a very big stretch of the imagination, if momentum gathers pace, then the risk of a messy unwind of carry trades allied with Japanese repatriation flows should not be ignored.

** U.S.A. – August labour data **

Warsh’s speech was notable for placing much more emphasis on the Unemployment Rate, seen steady at 4.1%, and the low level of weekly jobless claims (little changed at 206K), playing down Average Hourly Earnings and wages generally in terms of a key inflation outlook factor, and essentially omitting Payrolls, which are expected to rebound from the surprise -23K headline drop in July to +55K, as ever subject to revisions. Markets are however, creatures of habit, and it will probably take quite a long time to condition a shift in emphasis from the establishment survey Payrolls data to the household survey that provides the Unemployment Rate, meaning that initial market reaction will probably remain sensitive to Payrolls outliers and revisions, even if this does prove short-lived, i.e. gives way to more in-depth analysis of the Household survey data.

Disclaimer:
This material is provided for information purposes only and does not constitute investment advice, a recommendation, or an offer to buy or sell any financial instrument. The views expressed reflect market conditions and publicly available information as of the date of writing and may change without notice. No representation or warranty is made as to the accuracy or completeness of the information. Past performance is not indicative of future results. Readers should consider their own circumstances and, where appropriate, seek independent financial advice.

Risk Warning: Investments in Equities, Contracts for Difference (CFDs) in any instrument, Futures, Options, Derivatives and Foreign Exchange can fluctuate in value. Investors should therefore be aware that they may not realise the initial amount invested and may incur additional liabilities. These investments may be subject to above average financial risk of loss. Investors should consider their financial circumstances, investment experience and if it is appropriate to invest. If necessary, seek independent financial advice.

ADM Investor Services International Limited, registered in England No. 02547805, is authorised and regulated by the Financial Conduct Authority [FRN 148474] and is a member of the London Stock Exchange. Registered office: 3rd Floor, The Minster Building, 21 Mincing Lane, London EC3R 7AG.                  

A subsidiary of Archer Daniels Midland Company.

© 2026 ADM Investor Services International Limited.

Futures and options trading involve significant risk of loss and may not be suitable for everyone.  Therefore, carefully consider whether such trading is suitable for you in light of your financial condition.  The information and comments contained herein is provided by ADMIS and in no way should be construed to be information provided by ADM.  The author of this report did not have a financial interest in any of the contracts discussed in this report at the time the report was prepared.  The information provided is designed to assist in your analysis and evaluation of the futures and options markets.  However, any decisions you may make to buy, sell or hold a futures or options position on such research are entirely your own and not in any way deemed to be endorsed by or attributed to ADMIS. Copyright ADM Investor Services, Inc.

Latest News & Market Commentary

Explore the latest edition of The Ghost in the Machine

Explore Now