PLEASE NOTE: Due to conference commitments and planned leave, the next edition will be published on Wednesday 30 September.
- Trump-Xi meeting in focus as limited trade truce extension is digested; busier run of surveys, as expected SNB, Riksbank and Norges Bank rate decisions to digest, BoE perhaps the focal point of another barrage of central bank speakers, as rising energy prices and bond yields cast a long shadow
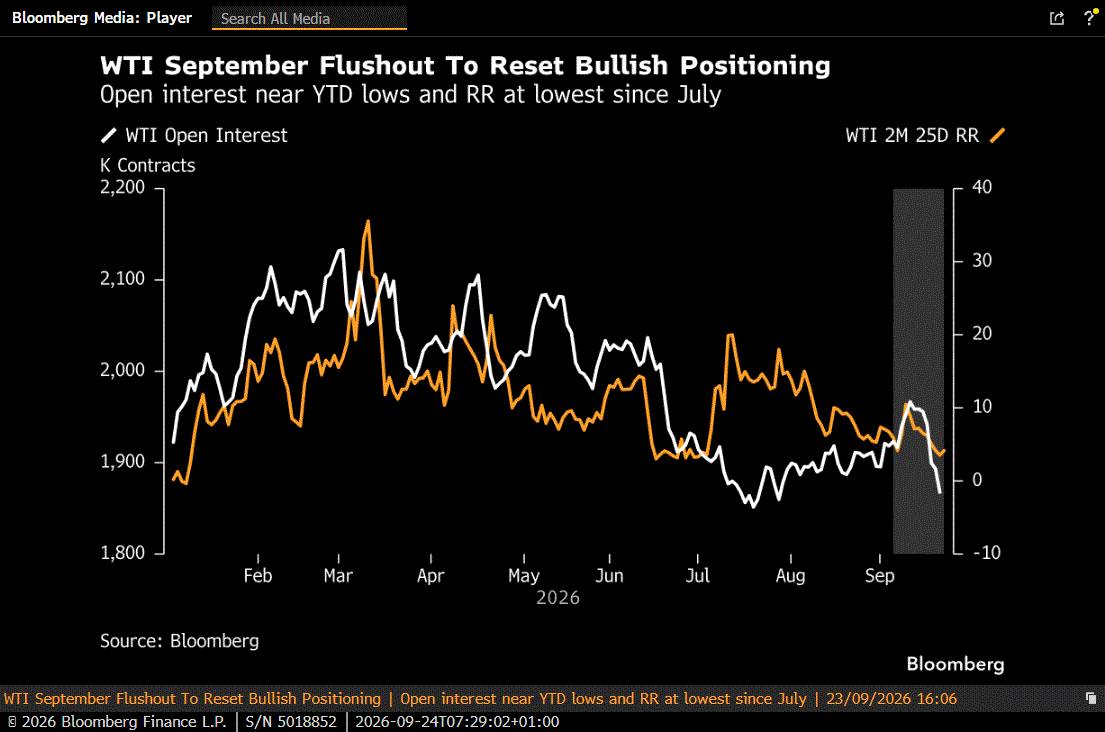
- Energy: rebound in crude prices confirms early week slide was a purge of excess speculative positions, more than genuine hope about improving diplomacy and supply relief
- Rising bond yields a reminder that diversification trades only go so far when USD rates are at multi-decade highs, also raising questions about financing of the AI investment boom
EVENTS PREVIEW
Geopolitics, Economic Data and Central Banks
While developments in the Middle East and around the Black Sea will continue to be closely monitored, with energy prices getting very choppy, it is the state visit of China President Xi to the US that will be the focal point for the day. There is also a busier run of data on tap, with Australian Unemployment, Japan’s flash PMIs, French Business Confidence and Germany’s Ifo Business Climate to digest ahead of US weekly jobless claims and New Home Sales. Another busy day for central bank speakers, perhaps most notably BoE’s Breeden, Dhingra and Lombardelli, given that it has been primarily ECB and Fed speakers until today, with Switzerland’s SNB and Sweden’s Riksbank holding rates as expected, and Norges Bank hiking rates a further 25 bps to 4.50%.
Energy Markets and Bond Yield Developments
The attached chart highlights that the early week sell-off in energy prices was heavily driven by specs reducing excess exposure, with open interest in WTI falling away very sharply and setting up the current rebound that more accurately reflects overall supply risks. But along with the hawkish shift from the Fed, this is also driving G7 government bond yields higher and spilling over into a broader risk-off move, serving as a reminder that diversification trades offer only limited protection with US long-term rates now back at pre-Global Financial Crisis levels, in turn also raising questions about financing the AI investment boom, above all for those companies which do not have the long-established and robust free cash flows that the Mag7 have.
USA/China – Trump/Xi Meeting
The two-month extension of the ‘trade truce’ had been effectively flagged by Secretary of State Rubio, that President Trump would have the opportunity to interact with China again later this year at APEC and G20 meetings, and looked to be ‘low-balling’ expectations for today’s meeting between the two, with Bessent saying the extension will allow time to work on a bigger trade deal. It confirms that the US wants to pressure
Disclaimer:
This material is provided for information purposes only and does not constitute investment advice, a recommendation, or an offer to buy or sell any financial instrument. The views expressed reflect market conditions and publicly available information as of the date of writing and may change without notice. No representation or warranty is made as to the accuracy or completeness of the information. Past performance is not indicative of future results. Readers should consider their own circumstances and, where appropriate, seek independent financial advice.
Risk Warning: Investments in Equities, Contracts for Difference (CFDs) in any instrument, Futures, Options, Derivatives and Foreign Exchange can fluctuate in value. Investors should therefore be aware that they may not realise the initial amount invested and may incur additional liabilities. These investments may be subject to above average financial risk of loss. Investors should consider their financial circumstances, investment experience and if it is appropriate to invest. If necessary, seek independent financial advice.
ADM Investor Services International Limited, registered in England No. 02547805, is authorised and regulated by the Financial Conduct Authority [FRN 148474] and is a member of the London Stock Exchange. Registered office: 3rd Floor, The Minster Building, 21 Mincing Lane, London EC3R 7AG.
A subsidiary of Archer Daniels Midland Company.
© 2026 ADM Investor Services International Limited.
Futures and options trading involve significant risk of loss and may not be suitable for everyone. Therefore, carefully consider whether such trading is suitable for you in light of your financial condition. The information and comments contained herein is provided by ADMIS and in no way should be construed to be information provided by ADM. The author of this report did not have a financial interest in any of the contracts discussed in this report at the time the report was prepared. The information provided is designed to assist in your analysis and evaluation of the futures and options markets. However, any decisions you may make to buy, sell or hold a futures or options position on such research are entirely your own and not in any way deemed to be endorsed by or attributed to ADMIS. Copyright ADM Investor Services, Inc.
