Macroeconomics: The Day Ahead for 22 September 2026

UN General Assembly and barrage of central bank meetings top the schedule, with a very light data calendar; Middle East and Black Sea conflicts still ruling the roost, even as AI investment euphoria gets back in the saddle.

  • Fed: generally neutral Goolsbee comments distinctly more hawkish, notable for highlighting the limits of looking through food and energy price pressures
  • Energy: sharp setback in crude and product prices yesterday less a case of more hopeful news, and rather more specs getting ‘stopped out’

EVENTS PREVIEW

Geopolitics and the UN General Assembly Take Centre Stage

Today’s schedule is all about central bank speakers and geopolitics, with a whirlwind of bilateral meetings as the annual UN General Assembly gets under way in New York, at which the conflicts in the Persian Gulf, Red and Black Seas will obviously feature very heavily.

The statistical schedule is unlikely to feature on markets’ radar, with a wider-than-expected UK PSNB budget deficit underlining the serious challenges that PM Burnham and Chancellor Healey face as they put together the late October annual Budget.

AI Euphoria Proves Resilient

Yesterday’s sharp rally in tech stocks served to show that AI euphoria (and related FOMO) has not evaporated, even if it remains subject to longer-term gnawing doubts around returns on extraordinarily high levels of investment and security/safety concerns.

Oil Prices: Diplomacy Hopes or Positioning Washout?

The sharp setback in oil and refined product prices was also instructive, given that the justification for the move referred to hopes for a return to diplomacy based on the US President’s comment that he might be open to meeting with Iran’s President on the sidelines of the UNGA, along with hopes for a rebound in shipments from Saudi Arabia and through the Strait of Hormuz.

But that looked like post hoc rationalization, with the sharpness of the move looking much more like specs getting ‘stopped out’, as the attached chart of Brent volatility and options skew would suggest.
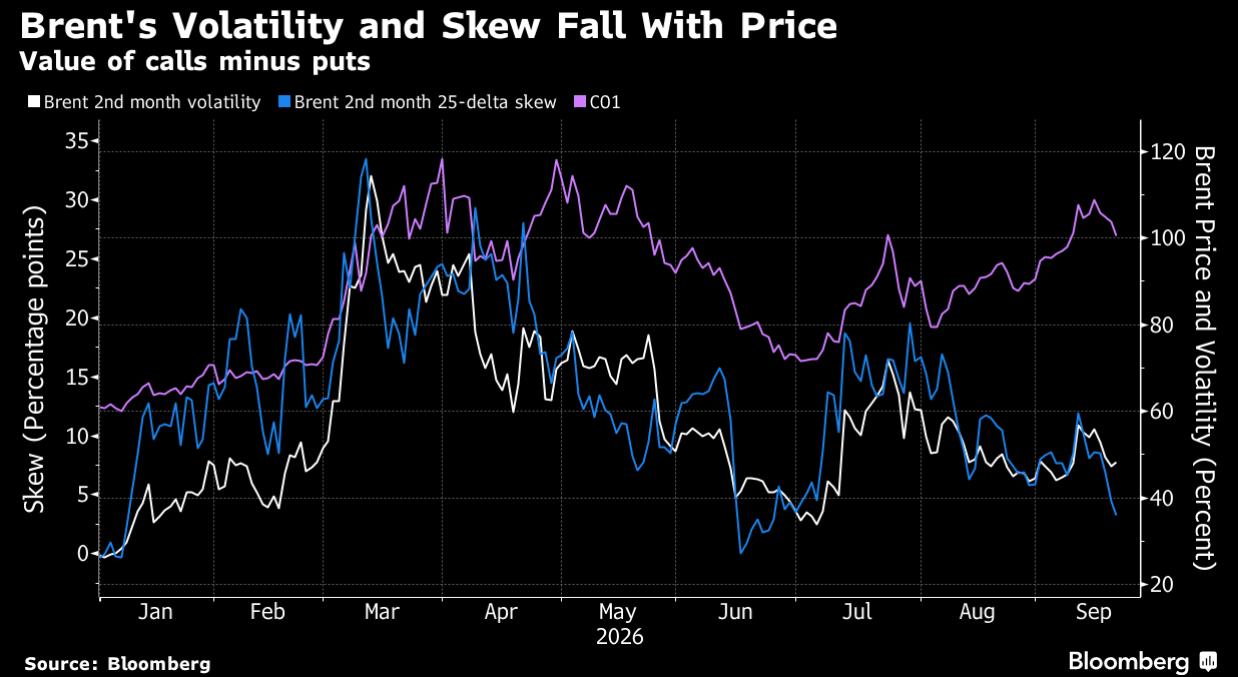
Chart Brent Crude Volatility and Skew

Indeed, the threat of a US diesel export ban, as US retail diesel prices touched $6.51 with only six weeks before the US mid-term elections, appears to be a more important consideration in terms of both physical supply bottlenecks and “on the ground” inflation risks.

Federal Reserve Signals and Interest Rate Risks

Today’s barrage of central bank speakers follows enlightening comments from Chicago Fed’s Goolsbee and St Louis Fed’s Musalem, whereby the Goolsbee comments were of greater interest given that he is typically in the middle on the hawk-dove spectrum, whereas Musalem generally leans to the hawkish side.

Of particular note were the observations:

“Oil, tariffs, and commodity prices — forecasters have spent more than a year pushing back the date when inflation was supposed to peak and start falling. … That’s not a comforting pattern.”

“We need evidence that these shocks are actually fading, or it’s hard to see a credible path back to 2% inflation — and harder still to justify continuing to look through them.”

“If the through line is that it’s coming from overheating demand, I think the implication is the rate response is more aggressive and more and more front-loaded.”

While these comments did not offer much in the way of guidance on timing, they imply that for the time being, every FOMC meeting is ‘live’ in terms of a potential further rate hike, and the focus shifts to the generally neutral Jefferson and Barkin, and the dovish-leaning Williams today.

Meanwhile, comments from ECB’s Lane overnight suggesting that inflation should get back to target by the middle of 2027 and noting that spillover effects have been very limited (thus far), were rather more neutral.

Disclaimer:
This material is provided for information purposes only and does not constitute investment advice, a recommendation, or an offer to buy or sell any financial instrument. The views expressed reflect market conditions and publicly available information as of the date of writing and may change without notice. No representation or warranty is made as to the accuracy or completeness of the information. Past performance is not indicative of future results. Readers should consider their own circumstances and, where appropriate, seek independent financial advice.

Risk Warning: Investments in Equities, Contracts for Difference (CFDs) in any instrument, Futures, Options, Derivatives and Foreign Exchange can fluctuate in value. Investors should therefore be aware that they may not realise the initial amount invested and may incur additional liabilities. These investments may be subject to above average financial risk of loss. Investors should consider their financial circumstances, investment experience and if it is appropriate to invest. If necessary, seek independent financial advice.

ADM Investor Services International Limited, registered in England No. 02547805, is authorised and regulated by the Financial Conduct Authority [FRN 148474] and is a member of the London Stock Exchange. Registered office: 3rd Floor, The Minster Building, 21 Mincing Lane, London EC3R 7AG.                  

A subsidiary of Archer Daniels Midland Company.

© 2026 ADM Investor Services International Limited.

Futures and options trading involve significant risk of loss and may not be suitable for everyone.  Therefore, carefully consider whether such trading is suitable for you in light of your financial condition.  The information and comments contained herein is provided by ADMIS and in no way should be construed to be information provided by ADM.  The author of this report did not have a financial interest in any of the contracts discussed in this report at the time the report was prepared.  The information provided is designed to assist in your analysis and evaluation of the futures and options markets.  However, any decisions you may make to buy, sell or hold a futures or options position on such research are entirely your own and not in any way deemed to be endorsed by or attributed to ADMIS. Copyright ADM Investor Services, Inc.

Latest News & Market Commentary

Explore the latest edition of The Ghost in the Machine

Explore Now