Written Commentary

There is plenty on today’s scheduled agenda to distract markets from the overarching theme of the conflicts in the Persian Gulf, Red Sea and Black Sea, even if energy price gyrations will continue to be a key driver of sentiment. There are China’s Trade, CPI and PPI data, Singapore’s Q3 advance GDP and MAS policy decision, along with Indian WPI, to digest, though the focus will primarily be on US CPI and the latest Fed Beige Book.
BofA, BlackRock, Morgan Stanley and State Street headline the run of US corporate earnings, with Rio Tinto’s Q3 production also on tap, as well as the last of this month’s Oil Market Reports from the IEA, which highlighted that while refined product supply chains are likely to remain under pressure, the crude oil market surplus is growing. For a discussion on this, please watch yesterday’s GI Daily Energy Podcast.
There is also a veritable deluge of central bank speakers, mostly, but not only, at IMF/World Bank meeting related events. Unsurprisingly, the IMF has ramped up warnings on the need for fiscal consolidation across the G7 and Eurozone, though it did single out the UK’s efforts over recent years as putting it on a more sustainable debt path than other countries.
As I have been at pains to point out for some time, the political and media narrative on the economic and fiscal outlook has been far too negative for much too long.
Today’s run of inflation and trade data does not alter the overall profile of current dynamics in the Chinese economy, underlining that domestic demand remains, at best, sluggish, while Autos, AI and energy transition related equipment continue to drive booming exports.
CPI was essentially in line with forecasts at 0.9% y/y headline and 1.0% core, with energy and travel related prices exerting some upward pressure, while food continued to drag. PPI at 5.0% y/y was well above forecasts, with Fuel & Power (13.6% y/y), Non-ferrous Metals (20.0% y/y) and Chemicals (12.6% y/y) pacing purchasing price increases, but other sectors highlighting the weakness in domestic demand, e.g. Construction/Non-metal Materials -2.3% y/y and Wood & Paper Pulp flat y/y.
As for Trade, exports were much higher than expected at 36.3% y/y, with semiconductor exports surging 108.1% y/y in value terms, though volume increases were a fraction of that. By contrast, auto exports were up around 50% in both value and volume terms.
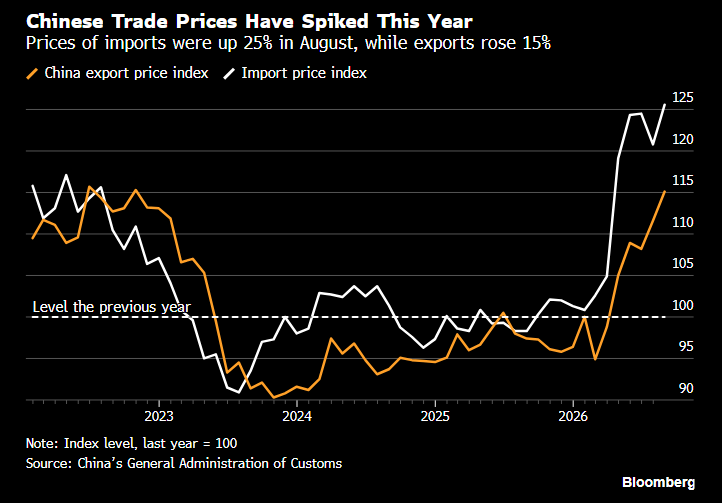
Imports at 31.0% y/y also largely reflect energy and commodity price pressures, with crude import volumes down 21.5% y/y, though rising modestly on the month, and soybean imports falling 7.7% y/y. Margin pressures on local manufacturers are above all evident when comparing China’s export and import prices, as shown in the attached chart.
CPI is seen jumping 0.6% m/m on the back of energy prices, mostly gasoline, with the y/y rate rising 0.2 ppt to 3.6%, though core is seen reasonably well contained at just 0.2% m/m, edging the y/y rate up to 2.5%.
Core CPI is likely to show that, while there are specific price pressures in areas such as airfares and education, and a likely rebound in medical care after a surprise fall in August, offset by a likely setback in used cars (as per the Manheim Index), these are not broad based, and housing price pressures are easing, even if higher mortgage rates are clearly impacting affordability and demand.
Barring a major surprise on core CPI, it should continue to allow the Fed to stick to a relatively cautious policy tightening path.
The Beige Book is likely to reprise September’s assessment of growth being modest, paced by a solid expansion in both Manufacturing and Services, and the latest labour report confirming a ‘low hire, low fire’ economy. The focus, however, will be on business outlook optimism, above all whether the latest upswing in energy prices is considered to be ‘manageable’, or whether more businesses suggest that they will have to pass through rising costs to customers.