Written Commentary

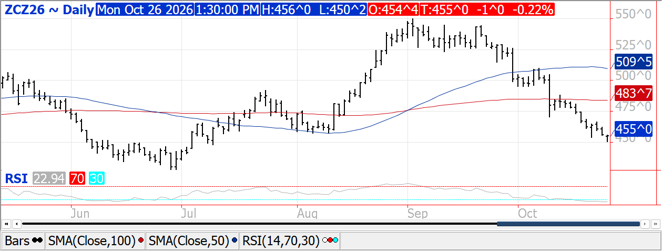
Prices were $.01-$.02 lower closing well off session lows while spreads firmed. Dec-26 traded to a fresh 3 ½ month low before bouncing. Money managers dumped another 85k contracts of corn in the week ended Tues. Oct. 20th, reducing their long position to 146k. Likely down to 135k as of Friday’s close. I look for US harvest to have reached 60% this weekend. Cattle on feed as of Oct. 1st at 11.372 mil. head were slightly below YA at 11.418 mil. and below expectations of 11.441 mil. Placements were down 12% vs. expectations of down 8.3%. Marketings were off 7%, in line with expectations. AgRural is reporting Brazil’s 1st crop plantings have reached 58%, just ahead of the YA pace of 55%. Export inspections at only 25 mil. bu. were a MY low and at the low end of expectations, well below the 66 mil. needed per week to reach the USDA export forecast. YTD inspections at 385 mil. are down 8% from YA, vs. the USDA forecast of down 4%. Noted buyers were Mexico with 13 mil. while Honduras took 5 mil. The path of least resistance remains lower until US demand improves and/or a more threatening SA forecast.
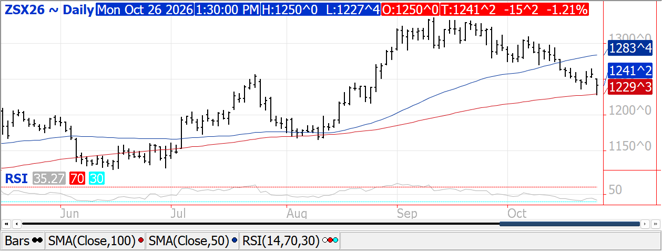
A late recovery in soybean oil enabled prices to close mixed across the complex. Beans were down $.12-$.16, meal was $5-$7 lower while oil was up 10-20 points. Spreads were mixed. Nov-26 beans fell to a 2-month low before bouncing after holding support near its 100-day MA and 50% Fibonacci retracement level near $12.29. Dec-26 meal also traded down to its 50% Fibonacci retracement at $337.90. Soybean prices gapped lower overnight, triggered by surprise election results in Brazil. Leftist Pres. Luiz Inacio Lula da Silva won an unprecedented 4th term securing nearly 52% of the vote. The Brazilian real slumped to a 10-month low vs. the US $$$. Conservative candidate Bolsonaro was considered a more favorable choice by the business community as he campaigned on fiscal discipline and corporate tax cuts. Now with Lula da Silva back for a 4th term, markets fear public spending and debt expansion will make the country’s public finances unsustainable. Bolsonaro refused to concede the results after voting was extended by over 2 hours on Sunday while calling on the Supreme Court to annul the election results. Chinese purchases of US beans are near 18 mmt while Sinograin will auction off another 512k mt of soybean tomorrow. MM’s unloaded another 30.5k contracts of soybeans, 19.5k meal and nearly 1.5k oil. Their combined long position at 481,487 contracts is at a 2-month low. The USDA attache in Brazil is forecasting their 2026/27 production at 184 mmt, just below the official USDA forecast of 186 mmt. AgRural is reporting Brazil’s soybean plantings have reached 40%, up from 26% LW and just ahead of the YA pace of 36%. US harvest likely reaching 80% this weekend. Export inspections at 91 mil. bu. were above expectations and the highest for any week in 2 years. Last week’s inspections were revised up by nearly 2.5 mil. bringing YTD inspections to 357 mil. are up 42% from YA vs. the USDA forecast of up 12%. China took 61 mil. bu. while Mexico took 10 mil.
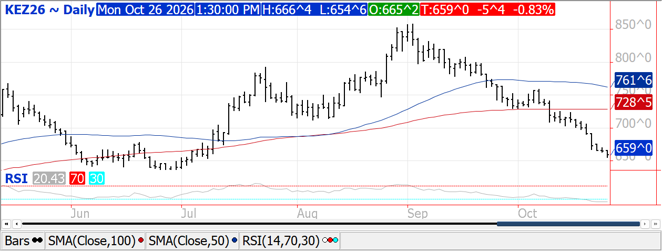
Prices were $.05-$.09 lower in 2-sided trade. CGO Dec-26 was down $.09 at $6.16, Dec-26 KC was $.05 ½ lower at $6.59 while Dec-26 MIAX was off $.07 ½ at $6.34. All 3 classes trading to fresh 3-4 month lows. Hopes for peace in the Black Sea combined with trying to find a price that attracts demand has pressured prices this month. At Friday’s close I’d estimate the MM short position in CGO wheat at 60k contracts, the largest in 3 months. Trilateral talks between US, Russia and Ukraine are slated for Nov. 10th, meanwhile the fighting continues. While US wheat is becoming more competitive in the global marketplace, demand remains weak. Export inspections at 7 mil. bu. were below expectations, a new MY low and well below the 14 mil. needed per week to reach the USDA forecast of 750 mil. bu. YTD inspections at 273 mil. bu. are down 35% from YA vs. the USDA forecast of down 17%. The Russian Govt. is set the begin purchasing grain from farmers later this month to help support domestic prices.
Risk Warning: Investments in Equities, Contracts for Difference (CFDs) in any instrument, Futures, Options, Derivatives and Foreign Exchange can fluctuate in value. Investors should therefore be aware that they may not realise the initial amount invested and may incur additional liabilities. These investments may be subject to above average financial risk of loss. Investors should consider their financial circumstances, investment experience and if it is appropriate to invest. If necessary, seek independent financial advice.
ADM Investor Services International Limited, registered in England No. 02547805, is authorised and regulated by the Financial Conduct Authority [FRN 148474] and is a member of the London Stock Exchange. Registered office: 3rd Floor, The Minster Building, 21 Mincing Lane, London EC3R 7AG.
A subsidiary of Archer Daniels Midland Company.
© 2026 ADM Investor Services International Limited.
Futures and options trading involve significant risk of loss and may not be suitable for everyone. Therefore, carefully consider whether such trading is suitable for you in light of your financial condition. The information and comments contained herein is provided by ADMIS and in no way should be construed to be information provided by ADM. The author of this report did not have a financial interest in any of the contracts discussed in this report at the time the report was prepared. The information provided is designed to assist in your analysis and evaluation of the futures and options markets. However, any decisions you may make to buy, sell or hold a futures or options position on such research are entirely your own and not in any way deemed to be endorsed by or attributed to ADMIS. Copyright ADM Investor Services, Inc.