Written Commentary

Prices were lower across the complex, again shrugging off flash sales to both China and unknown. Beans were down $.04-$.08, meal was $1-$3 lower while oil was off 45 points. Nov-26 beans slipped to a 2-month low with next support at $12.28. Dec-26 oil also fell to a 2-month low. Crush margins fell $.07 to $2.60 ½ bu. Harvest pressure combined with so-so demand and speculative selling has fueled the bearish sentiment across the Ag. space. Dry conditions across the Midwest this weekend enabled US harvest to get back on track. Dry conditions this week should allow US harvest to largely be completed by the end of the month. MM’s were net sellers of 14k contracts of soybeans, 10k oil while just under 1k meal. The combined MM long position as of last Tues. at 533k contracts remains historically high. That figure is likely below 500k as of today’s close. Wire services are reporting China’s pork production in the first 9 months of 2026 has reached 45.1 mmt, up 3.2% YOY as farmers increase slaughter to reduce excess hog inventories. Jan-Sept slaughter at 537.4 mil. pigs are up 1.4% from YA, while their pig herd fell 2.6% to 425.3 mil. head. Bloated capacity has resulted in farmers losing an estimated $40-$50 for every hog raised. AgRural reports Brazil’s plantings have reached 26%, just above the YA pace of 24%. US export inspections at 74 mil. bu. was well above expectations and the highest for any week in nearly 2 years. YTD inspections at 263 mil. are up 27% from YA vs. the USDA forecast of up 12%. China took 47 mil. bu., Mexico took 8 mil. while Germany and Japan both took 3-4 mil.
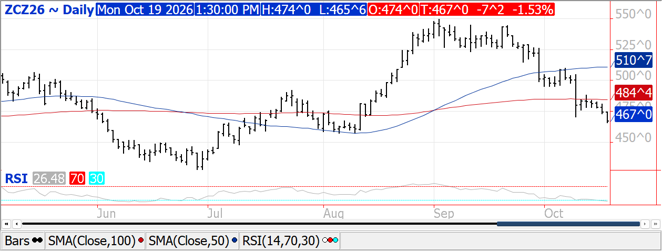
Lower closes across the complex with beans down $.02-$.03, meal was off $2-$3 while oil was off a few points. The soybean market largely shrugged off another round of flash soybean sales to China and unknown. A favorable harvest forecast combined with speculators shedding length in the agricultural markets has left the path of least resistance to the downside. Nov-26 beans slipped to a fresh 7-week low however bounced before reaching $12.50. Longer term support is at the 100-day MA at $12.25 ½. Support for Dec-26 meal is at its 50-day MA, currently $348. Inside trade for Dec-26 oil. Open interest from yesterday’s trade was up 3.2k contracts in soybeans, 4k in soybean meal while down a couple hundred contracts in oil. Crush margins were down $.04 at $2.63 bu. Export sales at 21 mil. was at the low end of expectations. YTD commitments are up 74% from YA vs. the revised USDA forecast of up 12%. Commitments to China are at 11.27 mmt as of Oct. 8th with another 5.64 mmt to unknown. Best guess on sales to China as of Oct. 8th stood at roughly 14.5 mmt. The USDA announced additional flash sales of 558k mt to China and 236k to unknown. Announced sales this week likely take commitments to China up to 16-16.5 mmt. If China’s 25 mmt of soybean purchases is already reflected in the current USDA export forecast of 1.695 bil. bu.(46.1 mmt) then sales to non-Chinese buyers must slip to 21 mmt, down 27% YOY. Current commitments to non-Chinese buyers at 430 mil. bu. are down only 13%. I’m leaning toward the current export forecast still too low. Meal sales at 366k tons were in line with expectations. YTD commitments are up 6% vs. the USDA forecast of up 11%. D4 RIN’s generated in September at 788.1 mil. were up 10% from August, however, fell further behind the level needed to reach the RFS mandates.
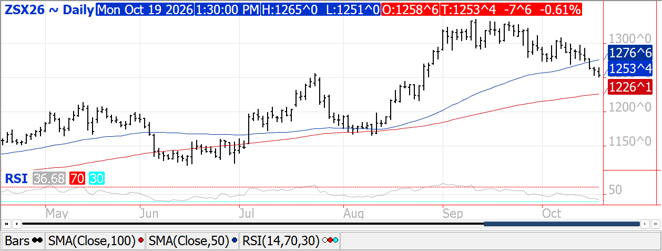
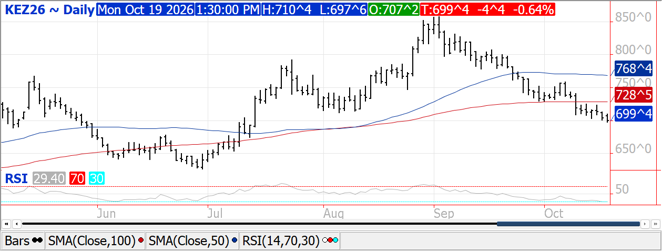
Prices ranged from $.04 to $.07 lower. CGO Dec-26 was off $.05 ¼ at $6.55 ¼, Dec-26 KC was down $.04 ½ at $6.99 ½, while Dec-26 MIAX was $.06 ½ lower at $6.70, all falling to fresh 2-3 month lows. APK Inform reports Ukraine’s grain shipments in the week ended Oct. 14th at 373k mt were up 29% from the previous week. Wheat shipments at 295.5k mt were up 24%. MM’s were net sellers of 12k contracts combined across the 3 classes of wheat, reversing their position to net short 6k contracts. They have been net sellers for 6 consecutive weeks while net short for the first time in 3 months. Export inspections at 9 mil. bu. were below expectations and below the 13 mil. needed per week to reach the USDA forecast of 750 mil. bu. YTD inspections at 265 mil. bu. are down 36% from YA vs. the USDA forecast of down 17%. IKAR reports the export price for Russian wheat at Baltic ports ended last week at $267/mt FOB, down $1 from the previous week. They forecast shipments in Oct-26 will likely range between 2.6-2.9 mmt down from their previous est. of 3 mmt.
Risk Warning: Investments in Equities, Contracts for Difference (CFDs) in any instrument, Futures, Options, Derivatives and Foreign Exchange can fluctuate in value. Investors should therefore be aware that they may not realise the initial amount invested and may incur additional liabilities. These investments may be subject to above average financial risk of loss. Investors should consider their financial circumstances, investment experience and if it is appropriate to invest. If necessary, seek independent financial advice.
ADM Investor Services International Limited, registered in England No. 02547805, is authorised and regulated by the Financial Conduct Authority [FRN 148474] and is a member of the London Stock Exchange. Registered office: 3rd Floor, The Minster Building, 21 Mincing Lane, London EC3R 7AG.
A subsidiary of Archer Daniels Midland Company.
© 2026 ADM Investor Services International Limited.
Futures and options trading involve significant risk of loss and may not be suitable for everyone. Therefore, carefully consider whether such trading is suitable for you in light of your financial condition. The information and comments contained herein is provided by ADMIS and in no way should be construed to be information provided by ADM. The author of this report did not have a financial interest in any of the contracts discussed in this report at the time the report was prepared. The information provided is designed to assist in your analysis and evaluation of the futures and options markets. However, any decisions you may make to buy, sell or hold a futures or options position on such research are entirely your own and not in any way deemed to be endorsed by or attributed to ADMIS. Copyright ADM Investor Services, Inc.