Written Commentary

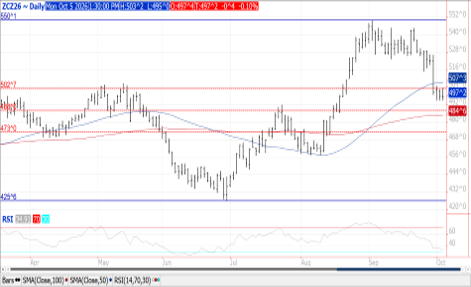
Prices were mixed and closed with very little change in choppy 2-sided trade while spreads weakened. Dec-26 held support at last week’s low of $4.95. Next support is at $4.88 with near term resistance at the 50-day MA at $5.07 ½. MM’s were net sellers of 36.6k contracts of corn, reducing their long position to 378k, a 5-week low. Through today’s close I’d guess is much closer to 315k. Very uneven rainfall across the Central Midwest last week. While significant harvest delays in some areas, good harvest progress was made across the S. Midwest and much of the ECB. I look for US harvest to have advanced 11% to 29% complete, matching the 5-year Ave. The USDA announced a flash sale of 129.5 mmt (5 mil. bu.) of corn to Mexico. Export inspections at 54 mil. bu. was in line with expectations, however below the 63 mil. needed per week to reach the USDA forecast. YTD inspections are up 4% from YA, vs. the USDA forecast of down 4.6%. Noted buyers were Mexico – 21 mil., Japan – 15 mil., while Colombia took 7 mil. AgRural is reporting Brazil’s 1st crop plantings advanced only 4% LW to 38% vs. 40% YA. For corn to bounce off recent lows we’ll likely need to see a bullish production figure from the USDA on Friday (below 15.7 bil.) and/or demand interest from China.
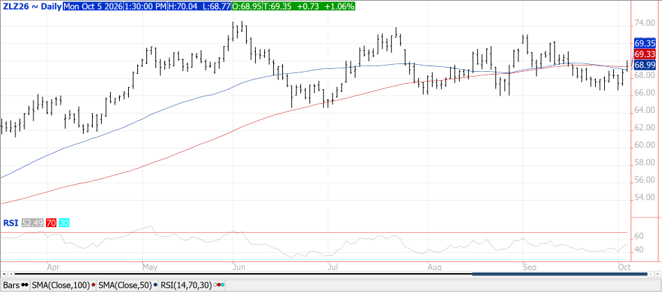
Prices were mixed across the complex with beans up $.02-$.03, meal was mixed while oil finished 70-80 points higher. Bean and oil spreads weakened while meal spreads were firm. Nov-26 beans stalled below $13 before pulling back. Dec-26 meal fell to a 1-month low before recovering. Dec-26 oil surged thru its 50 and 100-day MA resistance levels while briefly piercing $.70 lb. Favorable harvest conditions look to extend into mid-month after heavy rains in September delayed crop maturation and harvest across areas of the WCB and Central Midwest. CFTC data showed MM’s were net sellers of nearly 24k contracts of soybeans, nearly 9k oil while buying 15k meal. Index funds have been net sellers in soybean for 4 consecutive weeks. Crush margins improved $.11 to $2.45 ½ with BO PV improving to 50%. With China on Golden Holiday until Thursday, demand interest will likely be quiet however the USDA did announce a flash sale of 104k mt (3.8 mil. bu.) to an unknown buyer. Chinese purchases likely sitting at just over 14 mmt. Reports of mold and other disease issues in areas impacted by heavy rains last week likely supporting early strength. I expect harvest to have advanced 13% to 30%, below the 5-year Ave. of 35%. AgRural is reporting Brazil’s plantings have reached just over 7% vs. 9% YA. Export inspections at 42 mil. bu. was in line with expectations and above the 29 mil. needed per week to reach the USDA export forecast. YTD inspections are up 31% from YA vs. the USDA forecast of up 10%. China took 28 mil. bu. with Algeria taking 5 mil.
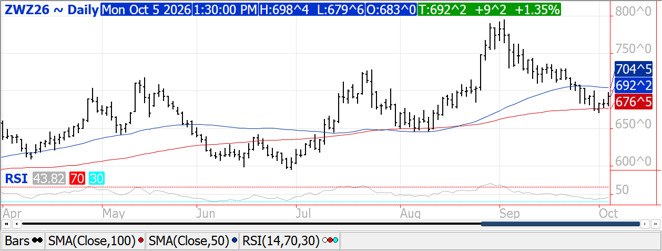
Prices closed $.07-$.11 higher in 2-sided trade. CGO Dec-26 was up $.09 ¼ at $6.92 ¼, Dec-26 KC was $.07 higher at $7.42, while Dec-26 MIAX was up $.10 ½ at $7.08 ½. The Russia/Ukraine war continues to intensify as Russia struck port infrastructure in Odesa while also destroying a vessel loaded with grain. Russia also struck a key bridge in Kyiv. Ukraine continues to target Russia energy infrastructure. Wire services are also reporting a Russian drone may have struck a vessel in the Black Sea in Romanian territorial waters killing 1 while 1 remains missing. 11 other crew members were rescued. Romania is a NATO member. Ukraine’s wheat exports since July 1st at 2.9 mmt are down 43% YOY, while 30% of the winter crop has been planted. Saudi Arabia reportedly bought 683k mt of wheat in their recent tender for 535k mt. Prices ranged from $334.66-$348/mt CF with an average of $339.24. The grain was sourced from Australia, the Black Sea region, the EU along with N. and S. America. Export inspections at 11 mil. bu. was in line with expectations, while below the 14 mil. needed per week to reach the USDA export forecast. YTD inspections are down 35% from YA vs. the USDA forecast of down 15%. MM’s have been net sellers across the 3 classes of wheat for 4 consecutive weeks.
Risk Warning: Investments in Equities, Contracts for Difference (CFDs) in any instrument, Futures, Options, Derivatives and Foreign Exchange can fluctuate in value. Investors should therefore be aware that they may not realise the initial amount invested and may incur additional liabilities. These investments may be subject to above average financial risk of loss. Investors should consider their financial circumstances, investment experience and if it is appropriate to invest. If necessary, seek independent financial advice.
ADM Investor Services International Limited, registered in England No. 02547805, is authorised and regulated by the Financial Conduct Authority [FRN 148474] and is a member of the London Stock Exchange. Registered office: 3rd Floor, The Minster Building, 21 Mincing Lane, London EC3R 7AG.
A subsidiary of Archer Daniels Midland Company.
© 2026 ADM Investor Services International Limited.
Futures and options trading involve significant risk of loss and may not be suitable for everyone. Therefore, carefully consider whether such trading is suitable for you in light of your financial condition. The information and comments contained herein is provided by ADMIS and in no way should be construed to be information provided by ADM. The author of this report did not have a financial interest in any of the contracts discussed in this report at the time the report was prepared. The information provided is designed to assist in your analysis and evaluation of the futures and options markets. However, any decisions you may make to buy, sell or hold a futures or options position on such research are entirely your own and not in any way deemed to be endorsed by or attributed to ADMIS. Copyright ADM Investor Services, Inc.