Written Commentary

The final quarter of 2026 gets under way with a busy run of data and central bank speakers, as the conflicts in the Middle East and the Black Sea, array of geopolitical and trade tensions, high energy prices and inflation concerns, and the AI investment boom remain the key overarching themes.
Statistically Manufacturing PMIs dominate the schedule, with a further record month for South Korean Exports (paced by a 263% y/y rise in semiconductor exports), a robust Q3 Japanese Tankan survey and September BoJ ‘Summary of Opinions’, and a blow out earnings report and revenue forecast from Micron Technology to digest, and a likely very hotly contended French Budget presentation.
As much as there appears to be increasing optimism about moves to resolve or at least temporarily halt the conflict in the Persian Gulf amid increasing energy exports and fewer skirmishes, such hopes have been dashed on many an occasion previously, and there is definitely no indication that the attacks on shipping and energy infrastructure in the Ukraine/Russia are likely to stop in the near term.
A renewed bounce in oil prices continues to compound the upward pressure on G7 bond yields, with US 10 yr yields hitting their highest since 2002, in what appears to be much less a case of a short-term hedge against rising long-term rates, and rather more a structural asset allocation to inflation and rates remaining high for much longer; as ever flows always send a much stronger message on underlying sentiment than market and media chatter.
The debate on when the Fed, ECB and BoJ will next hike rates does seem to be finally recognizing one element that has been rather underdiscussed, namely that back to back rate hikes are simply not on the agenda for the time being, as this would signal an aggressively restrictive policy stance and a steeper near-term rate trajectory, which would imply that central banks are behind the curve (arguably the BoJ remains so), as they were in 2022, but that is not the case now, especially given the array of political and economic uncertainties.
That said the lack of central bank guidance does leave markets with little choice other than to discount a steeper trajectory, especially given the underlying growth and trade volume resilience in developed economies.
Following on from the better than expected China PMIs, the array of Asian PMIs were largely robust, outside of Malaysia and the Philippines, paced by electronics/semiconductors along with autos, with orders and production generally picking up, but accompanied by continued signs of increased passthrough of energy and raw materials to selling prices, with a similar picture emerging from European PMIs.
The US Manufacturing ISM is seen edging up to 55.0 from 54.6, a more modest rise than the flash PMI’s jump to 57.0 from 53.9, reflecting a broader survey group that includes public sector entities. That said, key underlying components are projected to post somewhat stronger gains than the headline index: New Orders 54.7 vs. 53.7, Prices Paid 73.0 vs. 71.1 and Employment 52.0 vs. 51.1.
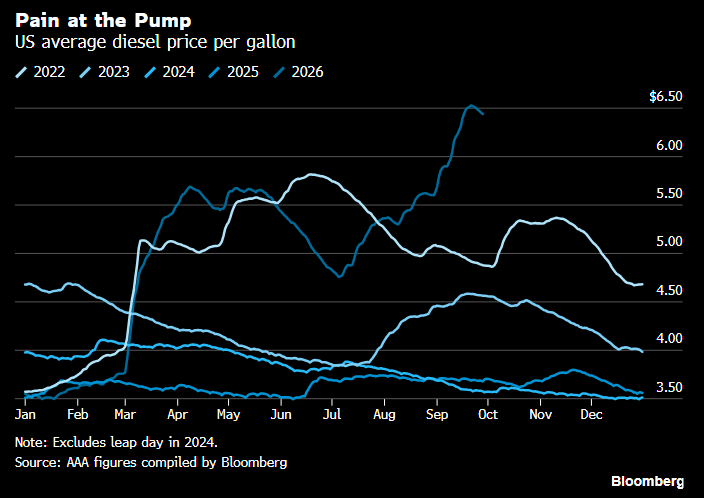
AI investment clearly underpins manufacturing strength, but a look at the attached chart of US diesel prices highlights the risk that persistently high road fuel and energy prices increase chances of a broader inflation spillover and the risk of demand destruction.