Written Commentary

Event risk is written very large today with the widening conflict in the Middle East, as the Houthis continue to attack Saudi infrastructure resulting in the closure of the Saudi East-West pipeline, compounding the impasse on Iran and the Strait of Hormuz, meeting central bank rate decisions in the US, Brazil, the UK and Japan over the next 48 hours.
Throw in the overnight UK inflation and Japan Trade data coming in ahead of US Retail Sales, Import Prices and the NAHB Housing Market Index, along with an intensifying debate about AI security, all making for a dizzying mix of factors to drive market sentiment.
For some, China’s Foreign Minister’s statement overnight urging “all parties to take effective measures to reopen the Strait of Hormuz at an early date”, and adding that China “does not want to see regional tensions spill over further into Yemen and the Red Sea”, signals increasing concerns about energy supply prospects, though it was in the context of a scheduled meeting with his Iranian counterpart, and per se little more than restating its prior concerns.
The CPI data was essentially in line with forecasts, with the 0.5% m/m, 3.1% y/y headline rise paced by energy and fresh food, but Services CPI holding at a still quite lofty 3.4% y/y along with core CPI at 2.6% y/y. As can be seen on the attached table, price pressures are very much concentrated in those two specific areas, with goods prices seeing no price pressures (Durables -0.1% y/y, Semi-Durables 0.2% y/y), by contrast to Energy and Seasonal Food jumping sharply higher to 10.2% y/y from 7.3% in July and just 4.6% back in June. Upward revisions to July PPI Input and Output, and August’s PPI coming in at 0.7% m/m, 3.7% y/y vs. expectations of 0.5% m/m, 3.3% y/y, also point to rising pass-through pressures.
While yesterday’s unemployment data suggested that labour demand continues to contract rather than levelling out as Q2 data suggested, and per se offered some support for the BoE majority’s ‘wait and see’ stance, the inflation data and the prospect of further upward price pressures in coming months make a strong case for a hawkish shift at tomorrow’s MPC meeting, and an increasingly strong possibility of a rate hike in November, when the BoE will also publish its latest Monetary Policy Report and accompanying updated forecasts.
Even if Jerome Powell was still in charge at the Fed, a 25 bps rate hike today, as is expected, would have been inevitable given that markets are discounting a 94% chance of a hike today, and anticipate two more rate hikes in December and March. For all that Warsh has been aiming to give the Fed more optionality on its policy rate path, his Jackson Hole speech effectively painted the FOMC into a corner, given that the latest CPI data confirm that underlying trends have not “meaningfully improved”, and, as he said: “We can be held accountable for delivering on our remit – the only true test of our credibility.”
Delaying a rate hike to the 27/28 October meeting (even closer to the mid-term elections) is not an option on that basis, above all as it would smack of political interference, given President Trump’s most recent comments on interest rates, but there may still be one or other dissent, though it would be much better if there were none, as it would strengthen the ‘independence’ credibility of the Fed, and Mr Warsh as manager, even if he does not appear to place much weight on the latter. Leaving aside Warsh’s dislike for policy guidance, the Fed and all other major central banks have no other choice, given the immense array of geopolitical and economic uncertainties, than to stick with a ‘meeting by meeting’ stance.
Naturally markets will then focus on the ‘dot plot’, which back in June (seemingly a very long time ago now) saw the rate path as steady to slightly higher in the near term, but anticipating some easing of policy in 2027 and 2028. That will definitely change, though there may be an even greater divergence of FOMC member opinions on the future path than was already manifest in June (see chart), perhaps above all with the ‘longer run’ estimates, not only for rates but also the PCE deflators.
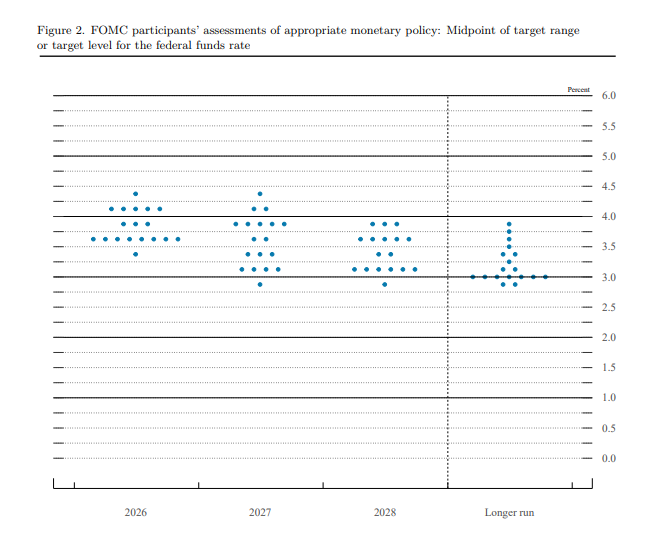
While Warsh restored a lot of credibility with his Jackson Hole speech, he still faces a big challenge in ensuring that he sticks with a clear analysis of the current economic situation and avoids the dismissive rhetoric of the July press conference that did much damage, while at the same time not making any commitments on the policy rate path. As for market reaction, the focus will be on how the Summary of Economic Projections impacts the US Treasury yield curve that has shifted overall higher but also flattened. But the performance of the USD may be of more significance, particularly given the fact that implied volatility is very low given the level of event risk (1-week implied EUR/USD at 5.6%), primarily a reflection of the fact that realized volatility is just a fraction of that at around 1.9%. Per se, markets are effectively discounting a relatively limited reaction to today’s decision, and implicitly to an even more challenging communications challenge for BoJ’s Ueda on Friday morning. Ahead of the FOMC decision, Retail Sales are expected to echo the labour data in signalling that the unexpected drop in July was an outlier, with headline seen up 0.8% m/m (vs. July -0.6%), boosted by gasoline prices and auto sales, and the core ‘Control Group’ measure rebounding 0.5% m/m after a drop of -0.4%, and as ever beware of revisions.