Written Commentary

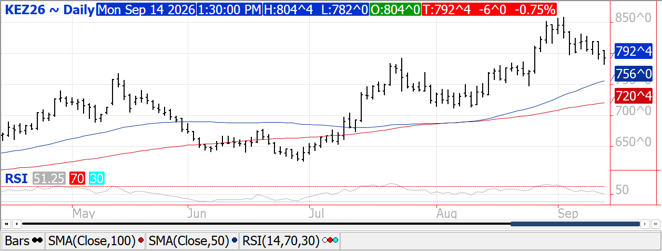
Prices ranged from $.03 to $.09 lower in choppy, 2-sided trade. CGO Dec-26 was $.03 ¼ lower at $7.22, KC Dec-26 was down $.06 at $7.92 ½ while Dec-26 MIAX was $.08 ¾ lower at $7.36 ¼. Prices turned lower after Pres. Trump stated Ukraine and Russian have agreed not to strike each other’s energy targets. Perhaps an agreement to allow the safe passage of agricultural goods is next ? Prices will continue to find underlying support as long as logistical disruptions continue. Higher than expected global stocks on Friday tilted the USDA data bearish. Stocks/use among exporting countries rose to 16.8%, up from 15.5% in August, however below 17.9% from YA. APK-Inform raised Ukraine’s production forecast 2.4 mmt to 25 mmt while lowering their export forecast 2 mmt to 10.5 mmt, vs. the USDA est. of 26 mmt and 12.50 mmt respectively. Seaborne grain exports from Russia in July/Aug at only 4.2 mmt, roughly half of the 8 mmt shipped YA. Export inspections at 17 mil. bu. were above expectations. YTD inspections are down 28% from YA, vs. the USDA forecast of down 15%. IKAR reports Russian wheat offers at Baltic Sea terminals ended last week at $274/mt FOB, down from $279/mt the previous week. They also estimated Russian exports have already reached 2 mmt in Sept.
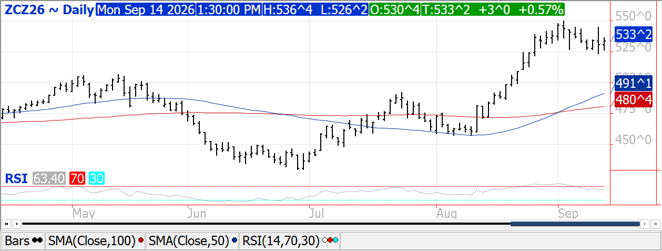
Prices were $.02-$.03 higher while spreads firmed in late trade. Dec-26 futures held within Friday’s range. Prices managed to recover after trading below $5.25 intraday on Friday. The USDA production and stocks were both slightly above the Ave. trade guess, however well within the range of estimates. I expect US crop ratings to slip another 1% to 55% G/E. I look for harvest to have advanced to 9% vs. the 5-year Ave. and YA pace of 7%. APK-Inform raised Ukraine’s production forecast 2.5 mmt to 32.3 mmt while lowering their export forecast 2 mmt to 22 mmt. AgRural places Brazil’s first crop plantings at 22%, up from 17% YA. US export inspections at 60 mil. bu. were in line with expectations. YTD inspections at 86 mil. are down less than 1% from YA, vs. the USDA forecast of down 4.6%. Mexico and S. Korea were noted buyers at 19 and 11 mil. bu. respectively. History shows that since 1990 the USDA lowered US corn yields in Aug. and Sept (like this year) 10 times. Oddly enough final yields were above the Sept forecast in 8 of those years while lower only twice. Global stocks/use among major exporting countries in 2026/27 fell to 9.3%, matching a 4-year low.
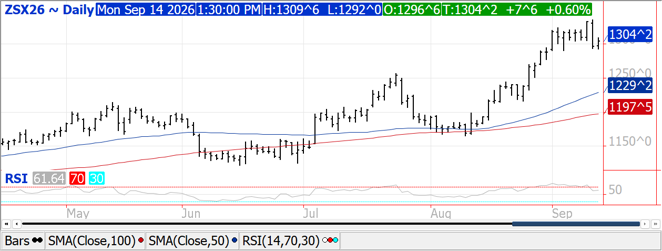
Prices were higher across the complex with beans up $.08-$.10, meal was $2-$4 higher while oil was up 45-50 points. Bean spreads weakened while product spreads were mixed. Nov-26 beans rejected trade below Friday’s low. Oct-26 meal jumped out to a fresh 2-year high, while Oct-26 oil is back consolidating near its 50 and 100-day MA’s. Weekend rains favored the ECB and SE with the next system pushing across the NW corn belt today. 100+ degree heat was limited to the S. Plains and Delta region while mid-90’s were common in the WCB and S. Midwest. Heavy rains are expected this week across the N. Midwest and Great Lakes region, while hot and dry in the South. US production at 4.535 bil. bu. was roughly 35 mil. above the Ave. estimate while stocks at 310 mil. were 10 mil. above the Ave. trade guess. The USDA has lowered soybean yields in Aug. only to raise them in Sept. 7 times since 1990. In 5 of those years final yields were above the Sept. forecast while below the Sept. estimate twice. Friday’s CFTC data confirmed the combined MM long position across the soybean complex as of last Tues. at 527k contracts was a new record high. Confirmed Chinese purchases of US soybeans at nearly 9 mmt with another 5.8 mmt to unknown. With additional flash sales last week, total to China likely sit just over 13 mmt. I look for crop ratings to slip 1% to 57% G/E with harvest in the single digits. APK-Inform raised Ukraine’s sunflower seed harvest .1 mmt to 13.58 mmt while lowering their soybean harvest 9% to 5.22 mmt. US export inspections at 25 mil. bu. were in line with expectations. YTD inspections at 34 mil. are down 16% from YA, vs. the USDA forecast of up 11%. Shipments to China were 12 mil. bu. Global stocks/use among major exporting countries in 2026/27 held at 18.5%, a 13-year low.
Risk Warning: Investments in Equities, Contracts for Difference (CFDs) in any instrument, Futures, Options, Derivatives and Foreign Exchange can fluctuate in value. Investors should therefore be aware that they may not realise the initial amount invested and may incur additional liabilities. These investments may be subject to above average financial risk of loss. Investors should consider their financial circumstances, investment experience and if it is appropriate to invest. If necessary, seek independent financial advice.
ADM Investor Services International Limited, registered in England No. 02547805, is authorised and regulated by the Financial Conduct Authority [FRN 148474] and is a member of the London Stock Exchange. Registered office: 3rd Floor, The Minster Building, 21 Mincing Lane, London EC3R 7AG.
A subsidiary of Archer Daniels Midland Company.
© 2026 ADM Investor Services International Limited.
Futures and options trading involve significant risk of loss and may not be suitable for everyone. Therefore, carefully consider whether such trading is suitable for you in light of your financial condition. The information and comments contained herein is provided by ADMIS and in no way should be construed to be information provided by ADM. The author of this report did not have a financial interest in any of the contracts discussed in this report at the time the report was prepared. The information provided is designed to assist in your analysis and evaluation of the futures and options markets. However, any decisions you may make to buy, sell or hold a futures or options position on such research are entirely your own and not in any way deemed to be endorsed by or attributed to ADMIS. Copyright ADM Investor Services, Inc.